

Welcome CFO Techstack Community 👋
Last week we shared a simple framework for choosing an app without falling for the demo. But some of the tools your business now relies on never go through that process at all. They're being built ("vibe coded") by individuals, with AI.
When that's managed well, teams move fast, bespoke processes are automated and the business keeps what they build. When it isn't, critical business IP can walk out the door. Read in full below.
Also this week, Florentina Sandu - Finalist for FTS Consultant of the Year - shares her best-of-breed tech stack!
When the person who built your AI tools walks out the door
Over the last few weeks we've shared what our Finance Leaders Advisory Council (FLAC) had to say about AI: what to build and what to buy, and how to stop the spend from running away.
This last piece is about a bigger claim that came out of the room: finance leaders may end up owning one of AI’s biggest risks, whether they planned to or not.
What's the risk nobody is planning for?
The biggest concern raised wasn't cost. It was what happens to a business's knowledge when AI tools get built ("vibe coded" as some would say) by individuals, under personal logins, with no one else able to see inside them:
"I think that's the biggest risk for me. I see these pockets of IP being developed in a business... I don't have my head around it at all."
The comparison one member reached for was one we all know too well: a spreadsheet macro that broke the moment the person who wrote it left. Except this time it's not a macro. It's reconciliation logic, board pack templates and entire reporting builds, sitting in someone's personal AI account. If they leave, the business doesn't just lose a person. It loses a critical process.
Is anyone else on top of this?
Not yet. Nobody in the room had it fully solved.
Teams are building their own tools and guardrails independently: customer service has one approach, the go-to-market team has another, engineering has a third, with no shared standard connecting any of it.
One member summed up the tension between letting people move fast and keeping any kind of control:
"How do you do quality control? How do you manage all sorts of other regulatory issues like privacy concerns?"
Real, sensitive data (names, emails, HR records) is already ending up in personal AI accounts. Not through malice, but that doesn't change how big of an issue this could be.
Why does this land on finance?
Finance leaders aren’t necessarily choosing to lead on AI governance. They’re being pulled into it, because the risks look a lot like problems finance already owns: key-person dependency, processes nobody else can check, and controls that only exist in one person’s head. As one member put it:
"Maybe this is a key topic that finance leaders are going to be the ones leading on... realising before anybody else."
That’s not finance being the department of “no”. Finance already knows what it takes to make a process reliable, auditable and not dependent on one person. AI tools need the same treatment.
Where do I start?
Not every AI build carries the same risk, and that’s a useful place to begin. Think about what each AI built tool can touch:
- It reads and presents. A dashboard or summary built on data you already have. If the builder leaves, you lose a nice view of the numbers, not the numbers themselves.
- It does a job. A small utility or connector that moves data from A to B or saves a manual step. Someone else needs to know it exists and how it works.
- It reads and writes. Anything that changes data in Xero, your CRM or payroll, or holds data itself. This is where a resignation can turn into a real problem.
With that in mind, a few sensible first moves:
- Find out what’s been built, and sort it. Ask each team which AI tools, prompts and workflows they rely on for recurring work, then put each one in a bucket above. You can’t govern what you can’t see, and you don’t need to govern a dashboard the way you govern something that posts journals.
- Lock down anything that writes. Move it onto a business account, not a personal login. Give it a named owner and a backup who can read how it works. The macro lesson still applies.
- Draw the line on sensitive data. A short, plain rule on what can’t go into AI tools (customer, employee and HR data) does more than a long policy nobody reads.
- Do it with IT, not around them. You know the processes and controls. They know the security side. Neither can solve it alone.
Where this leaves the community
We’ve deliberately spent these three pieces on the harder side of AI: what to build, what it costs, and who owns it. That’s not because we think AI is overhyped. It’s an exciting and empowering tool, and plenty of people are already talking about the amazing things they’re doing with it.
We covered the concerns because they’re the questions finance leaders in our community keep raising, and they deserve practical answers too.
If you want the other side, the real ways finance teams are using AI to save time and do things they couldn’t before, join us for Inside one finance leader’s AI playbook on Wednesday 18 November at 11am AEDT / 1pm NZDT, with AI expert Inbal Rodnay, and FLAC member, Jesse Chapman.
In the meantime, who owns the AI tools your team relies on today? Share how you’re handling it in The Stack Exchange.
___
COMMUNITY INSIGHTS
🎤 How I stacked it
Florentina Sandu, Migrate My Accounts
Finalist: FTS Consultant of the Year for 2026 🏆
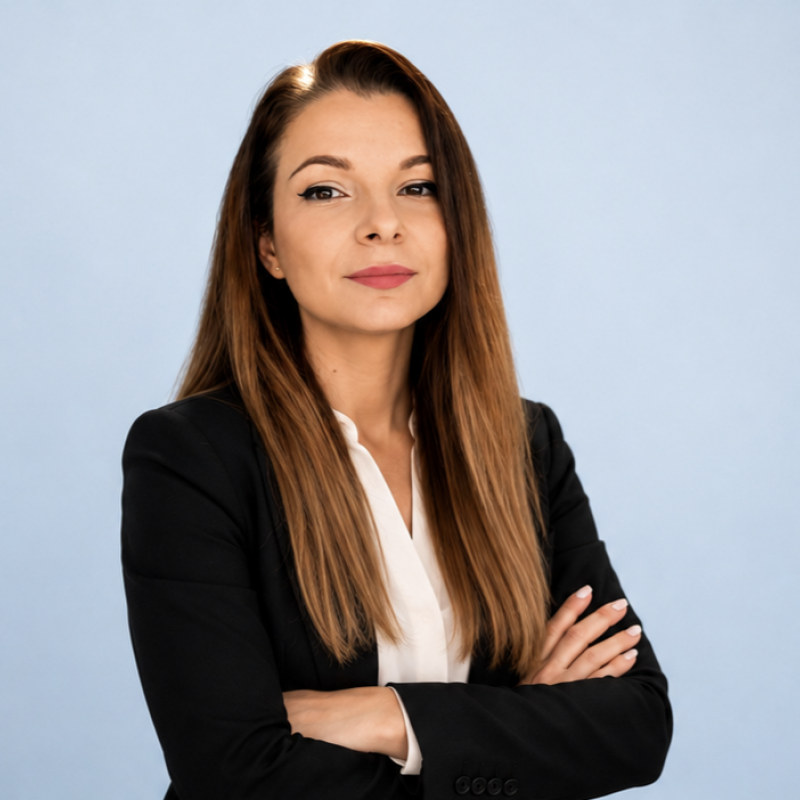
Migrate My Accounts brings together a group of Xero Migration Specialists who transfer historical data from any accounting system into Xero. As Founder, Florentina Sandu implements robust internal controls to ensure data accuracy and quality.
"The more migrations we complete, the clearer it becomes which apps clients actually need once they're on Xero. My go-to stack has evolved around that. I've become more selective about what I recommend too: if Xero can handle something well internally, I don't see a reason to add another app unless the client has a more complex process or there's a genuine gap. It's less about having lots of apps and more about recommending the right one when there's an actual problem to solve."
Here are the top apps Florentina recommends:
- Xero for General Ledger. The foundation of the stack and where every migration lands.
- Mayday for Intercompany. A go-to for automating intercompany processes for multi-entity clients.
- Joiin for Consolidation. Florentina's choice for simplifying group reporting and consolidation.
- G-Accon for Reporting. Her most-used app, supporting migrations and flexible monthly management reporting in Google Sheets.
- ApprovalMax for Purchase Approvals. Adds structured approval workflows for clients that need more control over purchasing and payments.
- Dext for Data Capture. Cuts manual entry for clients with more advanced document capture needs.
- Unleashed for Inventory and Manufacturing. Her go-to when clients need more complex stock and manufacturing functionality.
- Fishbowl for Inventory and Manufacturing. Another option for inventory-heavy businesses, because manufacturing processes vary so much from client to client.
- Lightyear for Accounts Payable. Recommended where clients have more advanced AP requirements than Xero handles internally.
- Make.com for Automation. Bridges gaps between Xero and other systems when the integration a client needs isn't there.
- ChatGPT and Claude for Problem Solving and Analysis. Used for troubleshooting, research and analysis, and for exploring automation ideas.
If you want to showcase your stack contact jack.thiel@getmayday.com
GIVE ME HOPE
Reader's question:
"More and more finance software vendors now call themselves 'AI-native'. What does that actually mean, and should it change how I choose my finance tools?"
Felix's answer:
'AI-native' is certainly a term we're seeing more and more, and it's worth unpacking. I consider it a marketing label over a category with a broad definition, so it's on us as potential customers to cut through the noise and understand what it means for each tool that uses it.
Generally, an 'AI-native' tool is a product, usually from a newer entrant, that has incorporated AI from the ground up. It's intrinsic to how the product works. To frame it further, consider the opposite: a tool that has bolted AI features on top of its core architecture, often cosmetic and of limited use. A simple test is to take the AI away. Would the product still serve its core function? If so, I wouldn't consider it truly 'AI-native', even if the vendor uses the term.
So is 'AI-native' a modern benchmark, a signal of a future-proofed app, that we should look for in every tool we evaluate? In my view, not on its own. I'd encourage anyone evaluating tools for their finance stack to look past the marketing copy and keep a laser focus on the workflows the app will manage.
Do these workflows really need AI? So much of our work is rules-based. Often the capability we need from a tool is reliable data management and automation, not another chat box. Where an 'AI-native' tool can be an advantage is the administrative, language-based work in finance, credit control for instance, where AI lets small teams manage it internally at scale.
More useful than the label, in a lot of cases, is how well a tool connects to the rest of your stack. Pre-built integrations give you secure, supported connections between the tools you use. Read and write access via an API or MCP goes further, letting your AI assistants work with the tool alongside you. This connectivity is a tangible capability, and unlike a marketing label, you can check it in the vendor's documentation.
So when a vendor tells you their tool is 'AI-native', I'd ask two things: is AI necessary for the job it's doing, and is the tool open enough to connect to the rest of your stack and your AI assistants? Those answers will tell you far more than the label.
Have a question you’d like answered? Submit your questions here.
EVENTS
Social: "Year End Close: Community Drinks" 🍻
🍻🎉👋 Come say hey! Make sure you book your spot, spots are running out now in all locations.
- Cape Town, Thursday 12 November: Book your spot
- Adelaide, Thursday 3 December: Book your spot
- London, Thursday 3 December: Book your spot [sponsored]
- Melbourne, Wednesday 9 December: Book your spot [sponsored]
- Sydney, Thursday 10 December: Book your spot [sponsored]
- Perth, Thursday 10 December: Book your spot
- Auckland [NEW], details TBC: Register your interest
Note, spots are limited so please only register if you intend to come along.
Dinner: CFO Techstack x Ramp: Euro Launch
If you're in London, join us for dinner 🎟️
To mark Ramp’s UK and European launch, CFO Techstack and Ramp are hosting an exclusive dinner for finance leaders in London on 1 December. If you’d like to come along, register your interest here.
Webinars: The Best in Finance x Tech
[APAC] Inside one finance leader’s AI playbook: CFO Techstack x ApprovalMax. Wednesday 18 November, 11am AEDT / 1pm NZDT. With Inbal Rodnay (AI Expert) and Jesse Chapman (Harris Real Estate). Register here
[APAC] The Hidden Cost of “It Works Fine”: Spend, Spreadsheets and Month-End. Mayday x Budgetly. Tuesday 24 November, 1pm AEDT / 3pm NZDT. With CFOs: Lisa Callaghan and Khalid Ahmed. Register here
THE STACK EXCHANGE
🧵 This week's top threads, from The Stack Exchange
The Stack Exchange is the place to connect with peers, stay on top of the latest apps and industry news, and work through the challenges that don't have an easy answer.
- Xero, Xero Ultra and additional Xero tracking categories
- Launch of the CFO Techstack app comparison
- CFO Techstack: Community update
Want to join the conversation? Sign up free here.
NEW IN THE WORLD OF CFO SOFTWARE
🗞️ News from the stack-o-sphere
- Float adds contact-level budgets. You can now link a customer or supplier from your accounting platform to a cash-flow budget. Read more
- Planday brings rostering into ChatGPT and Claude. Xero-owned Planday has launched verified connectors. Worth a look if labour is your biggest cost line. Read more
- Mayday's AI-accrual predictions get better. Now capable of identifying regular accruals that have been missed, and suggesting the journal to raise. Read more
WHAT THE DATA SAYS
📊 Stat of the week
Nearly 80% of CFOs say finance has a formal role in their organisation's AI-related decisions: 38% define or run the evaluation framework, and 41% are required approvers.
So what: finance is already at the table. But 53% say their main practice is reviewing AI usage costs after the fact.
Source: Deloitte CFO Signals Survey, Q3 2026 (200 CFOs at North American organisations with US$1B+ revenue).
MORE OF THE GOOD STUFF
And lastly, our top picks!
🎧 Podcast: Future Finance, “AI Is Accelerating Faster Than Humans Can Keep Up: What Should Finance Pros Do”. Listen here.
📝 Article: Basware CFO says AI upskilling requires ambition. Read here.
😆 Joke: We asked who owns the AI tool that builds our board pack. Same answer as the office plant: everyone relies on it, nobody waters it.
Why not forward this newsletter to someone you think would enjoy it?
Ready to level up your stack?
Join The Stack Exchange and connect with 500+ finance leaders who are building world-class tech stacks. Share insights, solve problems, and discover the best apps for your needs.
5,000+ subscribers

500+ active members